 Injoys
Social
A short written take on each piece of content: what changed and why it matters. Skim the point first, then follow through to the full article only for what interests you. Every take is drawn from real content, so the link takes you straight to the material it is based on.
Kim Man-deok and the 1795 Jeju Famine Relief
Kim Man-deok's aid isn't the total. The people and grain listed in the 1795 Jeju report on completed relief are state relief figures, not totals for her individual work. A separate 1796 entry in the Annals of King Jeongjo records the Jeju magistrate's report of her contribution. Treating the two records as one tally would assign the state's figures to her without support from the report. The article also explains King Jeongjo's permission for her to visit the capital and Mount Geumgang, including his order for towns along her route to provide provisions. It covers the repayment burden after food assistance and the issue of debt forgiveness in the completed-relief report. How she built her wealth and how her social status changed are separate research questions. Researchers of Joseon-era Jeju and readers checking historical claims can use the article to distinguish what each record establishes.
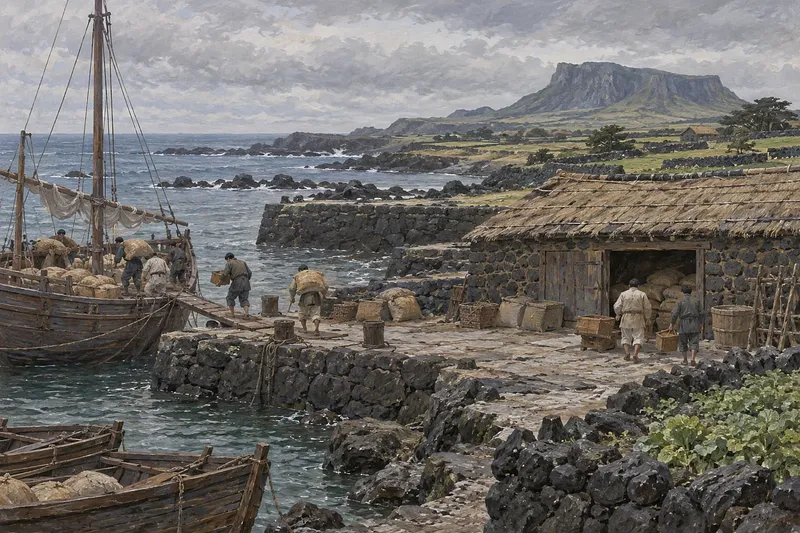
Irregular pay shifts employees' budget. Set aside payments and living costs until the next income arrives before assigning money to savings goals. An allocation based on an expected payment may not fit the amount deposited. The routine starts with the amount actually deposited in your bank account, so the plan uses money available now. The article sets out a 30-minute payday sequence: cover planned expenses, then choose where to hold any remainder. It explains how CMA, ISA, and pension savings differ, helping set contribution amounts based on when the money will be needed. A transfer instruction is not the same as a completed transaction. The final step is to confirm transfers and any needed investment purchases. Employees whose income varies can read the full routine for guidance on adjusting the amounts.
A manager in their 50s reviews results. Separate what the organization enabled from what you personally did before choosing your next role. Praise reflects the quality of your work, but it does not tell you whether you want to keep doing it. That distinction matters when a familiar role looks like the obvious next step. The article shows how to describe your contribution to company outcomes, including coordination and schedule management that can transfer to other roles. If you are considering a business, it also explains why living expenses should be separate from the cost of a manageable test. Poor sales are a reason to review demand and your offer, not your personal worth. For professionals making career and income decisions in their 30s, 40s or 50s, read the article to assess your current work and weigh a new income idea.
Midlife Crisis in Your 40s and 50s: What to Consider
For adults in their 50s, timing counts. Investment risk depends on when you will need the money and how much loss you can absorb, not on other people's returns. A midlife crisis is not an inevitable stage. Age alone does not settle separate questions about investing, retirement, family support and health. The article sets out how to assess those questions one at a time. A retirement budget covers living expenses, but a plan for daily activities and relationships helps you think through life after work. When deciding how much to support your children, consider both your own living needs and their goals. Persistent low mood or loss of interest should not be dismissed as aging; consider speaking with a professional. Adults in their 40s and 50s weighing these decisions can read the article for the criteria behind each one.
Operators seek investment with results. Hands-on work in an existing business can support funding talks and compensation negotiations. David Adelman's case explains that connection, but it does not establish that an individual earned 10 billion won in one year. Advice about earning a first $1 million is not evidence of that larger outcome. The article separates business revenue and assets under management from personal income and net worth. That distinction helps operators assess an earnings target using the right measures. It also explains why compensation criteria and payment terms must be agreed upon for operational results to translate into personal income. Operators weighing growth and compensation decisions should read the article. Investment and loans can expand a business, while the risk of losses and responsibility for operations remain.
Gemini Windows App 2026 Requirements and Shortcuts
IT admins: Gemini data may remain. Disconnecting a linked app does not remove data already in Gemini app activity; that data needs separate management. Account features need separate checks. Gmail and Google Drive integration differs in availability from personal intelligence, so access to one should not be taken as access to the other. Gemini for Windows requires Windows 10 or later and at least 8GB of RAM. Alt + Space opens the app, and users can change that shortcut in settings to fit their workflow. Nano Banana image generation is available to accounts without a subscription; video generation requires a paid subscription. Those differences help teams assess which accounts need which features. For teams supporting Windows 10 or later users with at least 8GB of RAM, the article brings the installation, account and activity-data requirements together. Read it before deciding how to set up the app.