 Injoys
Social
A short written take on each piece of content: what changed and why it matters. Skim the point first, then follow through to the full article only for what interests you. Every take is drawn from real content, so the link takes you straight to the material it is based on.
Money Luck: Lee Ha-young on Money Obsession and Rereading
Money Luck is not an income formula. Lee Ha-young's interpretation centers on the lack and fear attached to money. Its practical value is self-examination, but an individual's reading experience is not evidence that repeated reading will increase income or achievement. The article defines wealth as freedom from suffering over money. It then makes a necessary distinction: peace of mind and the actual ability to afford spending are separate measures. Keeping them apart helps readers avoid treating emotional relief as money available to spend. Repeated reading is described as returning to the same book and writing down a personal interpretation. “The world's balance” is presented as a metaphor for contributions that help other people, not a measurable rule of financial return. For readers assessing money beliefs, reading habits, or self-management frameworks, the article presents Lee's method and its stated limits. #DecisionMaking #EverydayFinance
Loan payments reshape investment plans. Set aside living and planned expenses before deciding how much savings can remain invested. The article compares deposits, interest-rate ETFs, and TDFs by risk and withdrawal terms. This helps match each portion of savings to its time horizon and an acceptable level of loss, rather than treating all available cash the same way. It then moves to portfolio design: set stock and bond targets, start with an affordable amount, check after-tax returns against the allocation actually held, and rebalance if needed. The ₩700 million example examines the calculation behind ₩3 million per month after tax, not a guaranteed income level. Beginners managing savings alongside loan repayments or planned expenses should read the article before setting an investment amount or target allocation. #AssetAllocation #EverydayFinance
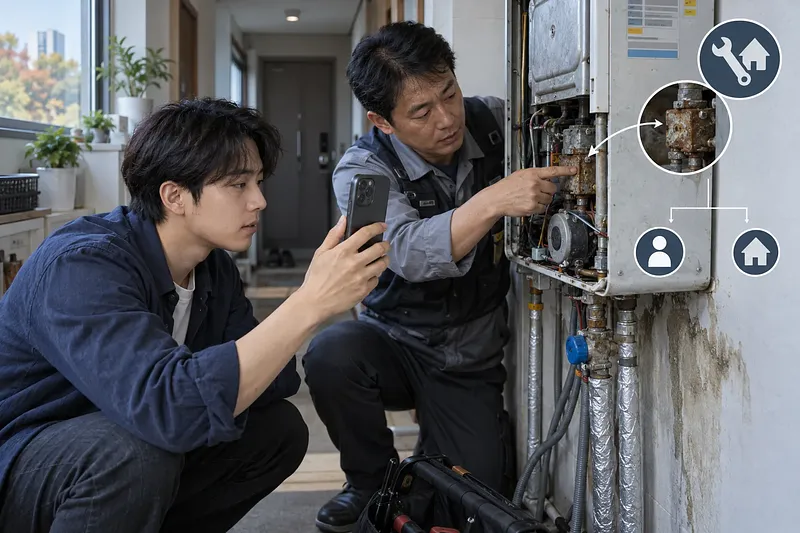
Renter Repair Duties and Housing Benefits for 2026
Renters must choose one tax treatment. One payment cannot be used for both the monthly rent tax credit and cash receipt income deduction. This distinction affects 2026 year-end tax settlement planning. Repair responsibility is assessed by the cause of the problem and its effect on use. The same principles apply to ordinary jeonse and monthly rental leases and help renters decide who should handle the work. For conversion, the rate is based on the deposit difference being changed into monthly rent. The guide distinguishes opposability, preferential repayment rights, and top-priority repayment for small-deposit tenants. These standards concern whether a lease holds against others and where a tenant stands in repayment. Their requirements differ, so they should not be treated as interchangeable. South Korean renters reviewing 2026 jeonse or monthly rental contracts, tax claims, or deposit protection can read the article first. Regular 2026 youth rent assistance applications closed at 4:00 p.m. on May 29.
A goal needs a verifiable result. That gives you a clear test for progress and a firmer basis for the next decision. Age and circumstances can change what is practical. Leaving those constraints undefined makes it harder to tell whether the action, the conditions, or missing help blocked progress. The article shows how to connect one small action to a specific starting situation instead of relying on a broad intention. It also explains what to record after acting: the result and the point where progress stopped. Those records become criteria for continuing or changing the approach. This framework applies when age, circumstances, or other constraints affect the plan. Read the article before planning the next attempt. #DecisionMaking #GoalAchievement
Sutteullier Lemon Verbena Dish Soap 2.5L x 4 Price
This post contains Toss Shopping ShareLink affiliate links, for which a commission is earned. Buyers weigh a 10L dish soap pack. Four 2.5L jugs are listed at ₩5,950 as of Sep 20, 2026, equal to ₩1,487.5 per jug. Volume is only part of the decision. The "highly concentrated" label does not establish the amount needed per wash or the product's cleaning power. Storage and likely consumption still determine whether four jugs are practical. The article separates fixed pack facts from details to confirm at checkout. It covers total volume and unit cost, then points buyers to the current product price, shipping fee, and selected configuration. The 4.7/5 rating from 736 reviews adds context, but it does not replace those checks. Households or workplaces with space for all four jugs and a realistic plan to use 10L should read the article before choosing this configuration. The decision then rests on usable quantity and final checkout details, not the product name alone. #DishSoap #DecisionMaking
Financial Judgment Peaks at 53? Asset Management Guide
Account access needs two decisions. Viewing and transaction permissions should be set separately when someone helps manage finances. The broader evidence also requires careful interpretation. In a 2009 study, age 53 was associated with fewer costly credit-transaction mistakes, not peak investment returns. Age-based differences in financial literacy scores cannot be converted into an individual's annual compound decline in judgment. The article applies those limits to an asset-management review. It explains why one late payment cannot establish dementia, even though increased late payments were observed before diagnosis. It also separates simpler account administration from investment diversification, since fewer accounts do not show whether a portfolio is diversified. Investors and people helping someone manage finances can use the guide to ask better questions without treating population research as a personal cutoff. Read the article before changing access or oversight. #BehavioralFinance #DecisionMaking