 Injoys
Social
A short written take on each piece of content: what changed and why it matters. Skim the point first, then follow through to the full article only for what interests you. Every take is drawn from real content, so the link takes you straight to the material it is based on.
Applying for UK Pension Credit 2026–27: Weekly Guarantee Amounts and the 3-Month Backdating Rule
Understanding Pension Credit rules can help older households plan their income and avoid losing support through a late application. For 2026–27, the standard weekly Guarantee Credit amounts are £238 for a single person and £363.25 for a couple. Assessable capital above £10,000 is treated as weekly income at £1 for every £500, or part of £500, over the threshold. Additional amounts may apply for disability, caring responsibilities, dependent children, qualifying young people or recognized housing costs. The article also covers applying up to four months before State Pension age, the official application process and the maximum three-month backdating rule. #PensionCredit #UKPension
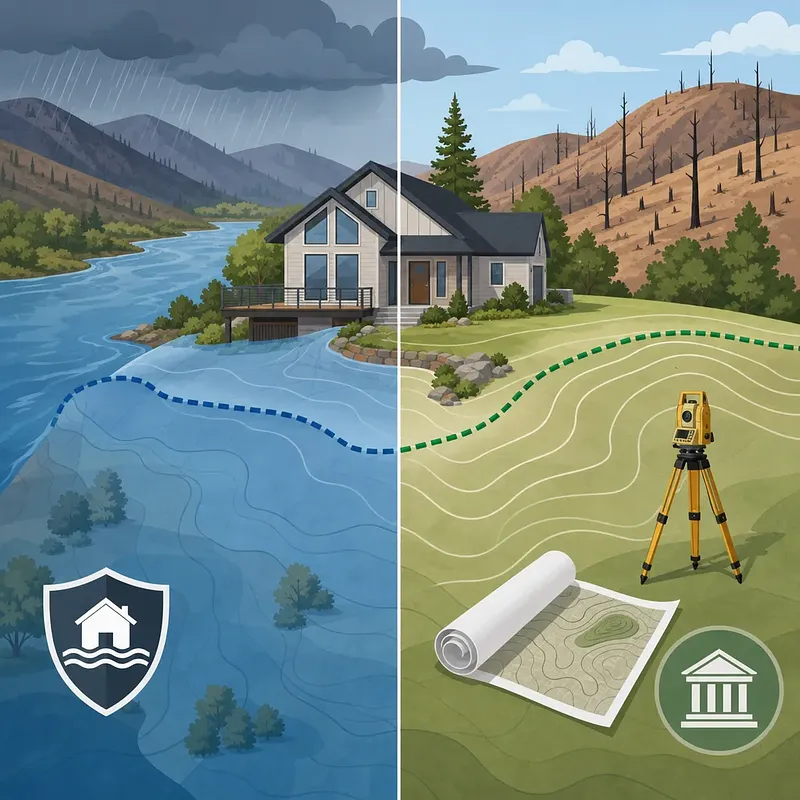
Flood-zone information can affect property financing, insurance planning, and risk assessment. FEMA’s Flood Map Service Center lets users search current official maps by address, place name, or coordinates—and checking the map’s effective date is an important part of that review. This article explains how A and V zones generally relate to Special Flood Hazard Areas, why an X designation does not eliminate flood risk, and when insurance may be required for certain federally related loans. It also outlines the NFIP’s standard 30-day waiting period and exceptions involving mortgage transactions, newly designated high-risk zones, and certain post-wildfire floods. For disputed mapping, it introduces FEMA procedures such as LOMA and LOMR requests. #FEMA #NFIP #FloodInsurance
Medicare Part D Extra Help can make prescription coverage more affordable, but understanding the 2026 eligibility rules is essential. The standard limits are $23,940 in annual income and $18,090 in assets for an individual, or $32,460 in combined income and $36,100 in assets for a married couple living together. Approved enrollees receive a $0 deductible and pay no more than $5.10 for generic prescriptions and $12.65 for other brand-name drugs. People with Medicaid, a Medicare Savings Program, or both SSI and Medicare generally qualify automatically. Others may apply through SSA at any time—there is no fixed annual deadline. Individual review may be available for applicants affected by earned income, dependents, or residence in Alaska or Hawaii. #Medicare #PartD #ExtraHelp
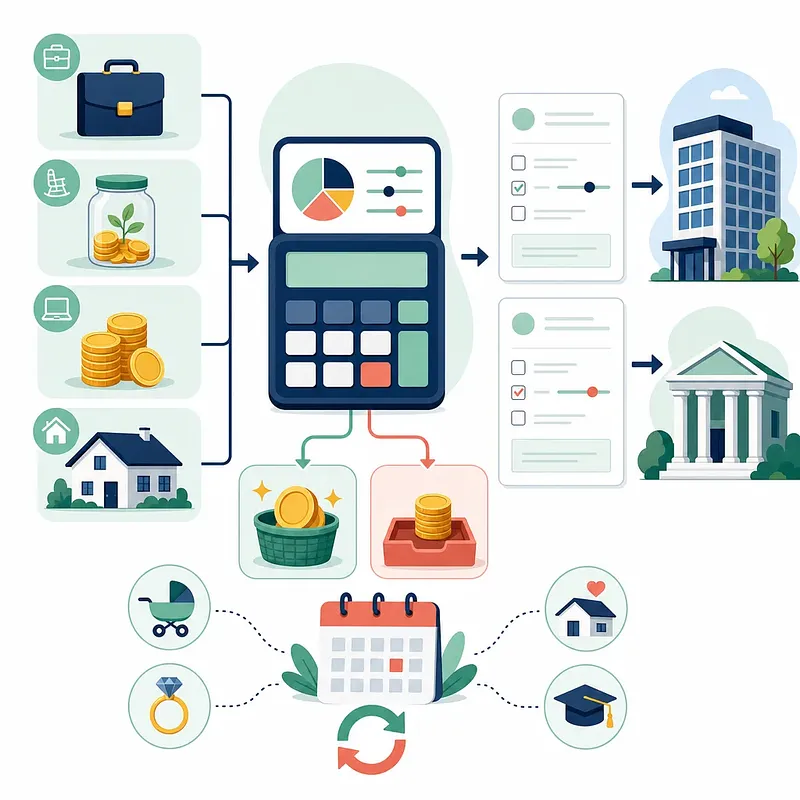
Federal tax withholding can become outdated when income, deductions, jobs, or family circumstances change. The 2026 IRS Tax Withholding Estimator helps taxpayers compare projected federal income tax with the amount expected to be withheld by year-end. This guide explains which documents to gather, including recent pay or pension statements, the latest federal tax return, and records of other income and deductions. It also covers the estimator’s new questions about qualified tips, overtime compensation, car loan interest, and the additional deduction for seniors. If an adjustment is appropriate, users can download a prefilled Form W-4 or W-4P. The result is an estimate—not a filed return or refund approval—but it can support more informed withholding decisions. #TaxWithholding #IRS
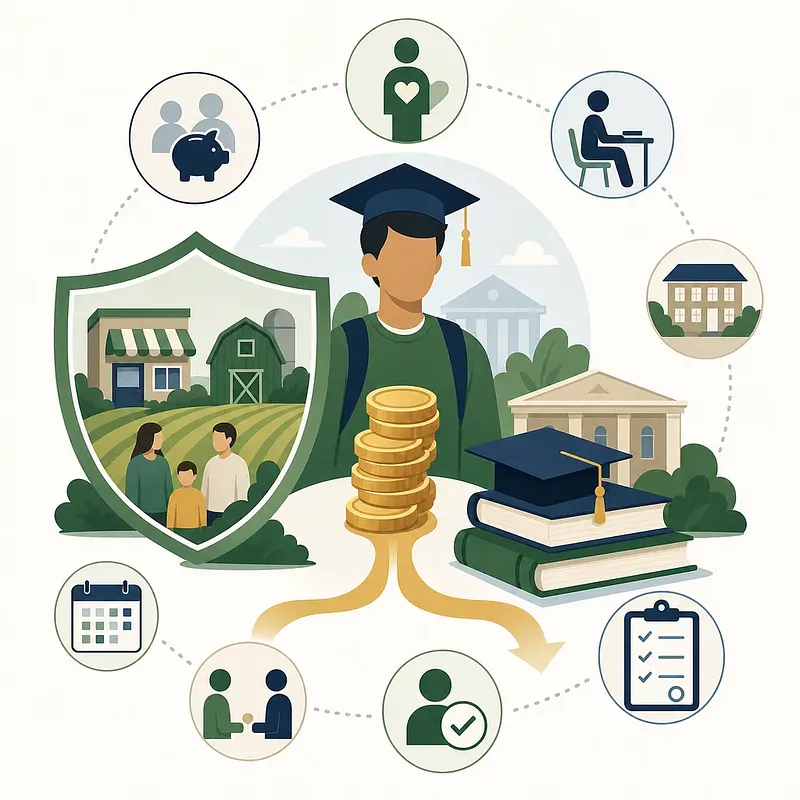
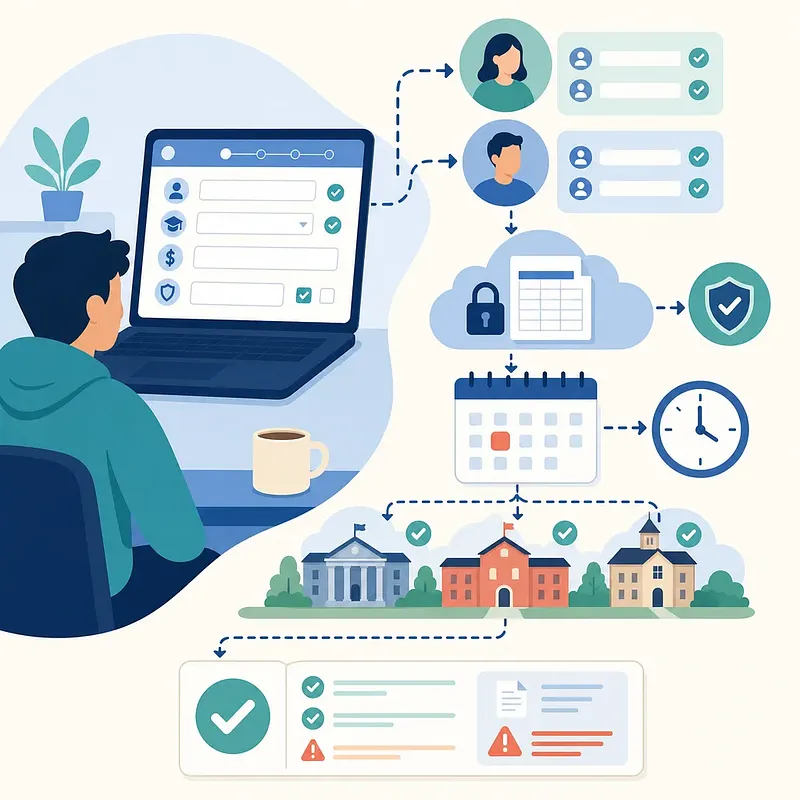
The 2026–27 FAFSA introduces details that students and families should understand before filing. The federal submission deadline is June 30, 2027, at 11:59 p.m. Central Time, but state and institutional priority deadlines may be significantly earlier, especially where funding is limited. The scheduled maximum Federal Pell Grant award is $7,395, although individual awards depend on financial need, enrollment intensity, attendance period, and school-determined costs. Revised asset rules also exclude the net worth of qualifying family businesses with no more than 100 employees and family farms where the family resides. This guide explains account preparation, contributor invitations, IRS data consent, and the post-submission checks that help identify errors. #FAFSA #FederalStudentAid
Can You Use a U.S. College Financial Aid Refund for a Laptop, Textbooks, and Living Expenses?
A college financial aid refund is the amount remaining after grants, scholarships, and loans are applied to tuition and other school charges. It is not necessarily “free money,” and FAFSA itself is only the application used to determine federal aid eligibility. Students may be able to use refund funds for a laptop, textbooks, reasonable housing, food, and transportation, depending on the school’s cost of attendance and the terms of each aid source. Tax treatment also varies: scholarships and grants used for certain living expenses may be taxable, while loan proceeds generally are not income. Enrollment changes matter as well. Withdrawing, not participating in classes, or reducing credits may require part of the refund to be returned. Understanding the source and conditions of each dollar can help students avoid unexpected tax or repayment issues. #FinancialAid #HigherEducation