Skip to content
Injoys
Knowledge Base 🇰🇷 South Korea

This content applies specifically to South Korea.

YouTuber Taxes: Registration and VAT Exemption Criteria

YouTubers must report recurring income from ads, sponsorships, and support as business income. Key things to check include whether the business is subject to VAT or exempt based on its employees and facilities, the simplified taxation threshold, filing dates, and overseas withholding tax considerations.

Listen or read this article

16:19

Listen, or read the text only.

YouTuber Taxes: Registration and VAT Exemption Criteria

Kokoro 82M AI-generated voice 17 min read

0:00 16:19

Advertisement

Download audio

File name
youtuber-tax-income-vat-business-registration-en.mp3
Format
MP3 (audio/mpeg)
Duration
16:19
File size
11.2 MB
Engine
Kokoro 82M

This audio was generated by AI.

You may download and use it freely for personal use.

YouTuber Taxes: Registration and VAT Exemption Criteria

12 min read

YouTuber Taxes: Registration and VAT Exemption Criteria
YouTubers must report recurring income from ads, sponsorships, and support as business income. Key things to check include whether the business is subject to VAT or exempt based on its employees and facilities, the simplified taxation threshold, filing dates, and overseas withholding tax considerations.
If you earn income from videos on an ongoing, recurring basis, you must register as a business.
Businesses exempt from VAT must still check their comprehensive income tax and business status reporting obligations.
The general threshold for simplified taxation, expanded in July 2024, is total sales of less than 104 million won in the previous year.
Comprehensive income tax is calculated after accounting for necessary expenses, deductions, and other factors, not on sales alone.
Google's U.S. tax withholding does not replace reporting income in Korea.
YouTubers who regularly earn income from advertising, sponsorships, or viewer contributions must file taxes. VAT-exempt businesses must also file comprehensive income tax returns. The amount they actually pay depends on deductible business expenses and tax deductions. Whether they have employees and facilities determines their business classification.
The simplified VAT threshold follows the standard revised in July 2024, and the filing dates follow National Tax Service guidance for the 2025 tax year.
What YouTuber income must be reported?
Income earned repeatedly from video activities for profit is business income. It is wrong to assume that only advertising income must be reported. Contributions that viewers send to a personal bank account in connection with broadcasts are also included. The National Tax Service says this income must be reported on a comprehensive income tax return. National Tax Service guidance on comprehensive income tax filing
Type of income | Records to check YouTube advertising income | Platform earnings and payment statements Corporate sponsorships and fees for promotional videos | Contracts and settlement statements Platform contributions and contributions to personal bank accounts | Contribution records and bank account transactions Income from events, lectures, and other activities | Payment statements and contract terms
The National Tax Service identifies advertising, contributions, corporate promotions, and events as types of creator income. However, one-off activities may be classified differently. If it is difficult to determine whether an activity is an ongoing business, organize your activity records and check. National Tax Service overview of solo media creators
Do employees and minors also have to file?
People with regular jobs should also check whether they need to file a comprehensive income tax return if they earn recurring income from videos. Their employer's year-end tax settlement does not cover video business income. A comprehensive income tax return also reflects employment income that must be combined with other income. National Tax Service overview of comprehensive income tax
Being a minor does not, by itself, exempt taxable income. If family members run a channel together, however, they must determine to whom the income actually belongs. If the person appearing on the channel, the person signing contracts, and the person receiving the income are different, check with the tax office responsible for your area.
Business registration and taxable versus exempt status
If you earn income from videos on an ongoing, recurring basis, you must register as a business. Registration is not a procedure you choose only when it offers tax savings. Whether a business is taxable or exempt is determined by its actual employment arrangements and business facilities.
The National Tax Service's “Tax Guide for Solo Media Creators” states:
Both taxable and exempt businesses must file comprehensive income tax returns.
Classification | Criteria | Industry code | Basic filings Media content creation business | Employs staff or has physical facilities for business use | 921505 | VAT and comprehensive income tax Solo media content creator | Has neither employees nor physical facilities for business use | 940306 | Business premises status report and comprehensive income tax
Running a channel alone does not automatically make you a VAT-exempt business. The National Tax Service gives professional filming equipment and a separate studio as examples of physical facilities. If it is unclear whether facilities are used exclusively for business, check before registering. National Tax Service tax guide for solo media creators
How is simplified VAT taxation different from exemption?
Simplified VAT taxation simplifies how VAT is calculated. Exemption means VAT does not apply to the services in question. The two systems differ starting with the criteria used to determine eligibility.
The general threshold for simplified VAT taxation is less than 80 million won in the previous year's sales, including VAT. The threshold was expanded in July 2024, so you should not simply apply the previous 80 million won threshold. National Tax Service guidance on changes to simplified VAT taxation
Classification | What to check | Exempt from comprehensive income tax? VAT-exempt business | Type of services provided and requirements concerning personnel and physical facilities | No Simplified VAT taxpayer | Sales threshold and exclusions from simplified VAT taxation | No General VAT taxpayer | VAT classification, including eligibility for simplified VAT taxation | No
Even if sales meet the threshold, simplified VAT taxation may be unavailable because of the type of business or other factors. Check your business registration to see which classification applies. You can also check the eligibility requirements in the National Tax Service's VAT guidance. National Tax Service overview of VAT
Zero rating for overseas advertising income
Overseas advertising income may qualify for zero-rated VAT if it meets the requirements. Zero rating applies a VAT rate of 0%. Unlike an exemption, it is a taxable transaction, so filing and supporting documentation are required. Do not treat domestic sponsorship income the same way. National Tax Service VAT guidance for creators
How much tax do YouTubers pay?
Monthly income alone cannot determine the final comprehensive income tax amount. Business income is calculated by subtracting deductible business expenses from gross income. Other income that must be combined with it, along with deductions, is then taken into account. This is why people with the same sales can owe different amounts.
When filing based on accounting records, the basic calculation follows these steps:
· Add together business income from advertising, sponsorships, contributions, and other sources. · Subtract allowable business expenses to calculate business income. · Account for other income that must be combined with it and for income deductions. · Apply the tax rate, then account for tax credits and taxes already paid.
Deductible business expenses are costs incurred for the business. Accounting records of income and expenses provide the basis for the calculation. The type of records required depends on factors such as the type of business and income level. National Tax Service guidance on accounting records and foreign tax credits
Are all video production costs deductible?
You cannot report personal living expenses as video production costs. For meals or purchased items, check whether the expense was actually related to the business. Keep receipts and record what the expenses were for. National Tax Service response concerning business owners' meal expenses
· Editing and production service fees: Check contracts and proof of payment · Filming location rental: Check the lease and records of business use · Equipment purchases: Check whether the equipment is used for business and how the cost should be recorded · Expenses with both personal and business use: Separate the business-related portion
High expenses alone do not create a tax refund. A refund arises if taxes already paid exceed the final tax assessed. Business income subject to 3.3% withholding in Korea must also be included in the final calculation. National Tax Service guidance on prefilled tax returns
Comprehensive income tax and VAT filing schedules
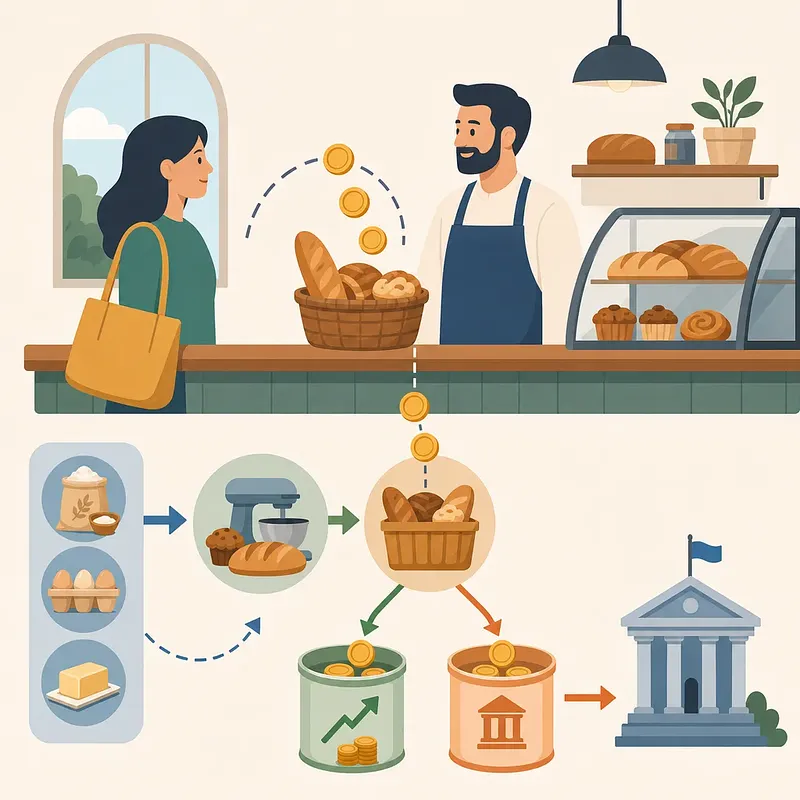
The usual comprehensive income tax filing period is May of the year after the income is earned. The statutory period runs from May 1 through May 31. Those submitting a confirmation of accurate tax filing have until June 30. If a deadline falls on a Saturday or public holiday, it is extended to the following day.
The general filing deadline for the 2025 tax year was June 1, 2026. Income earned in 2026 must, in principle, be reported in May 2027. Check the National Tax Service's filing guidance for year-specific exceptions. (Verified: For some taxpayers eligible for tax administration support for the 2025 tax year, the payment deadline was extended by 3 months from June 1, 2026, to August 31, 2026 · Source nts.go.kr · Checked 2026-10-05) National Tax Service comprehensive income tax filing and payment deadlines
Filing type | Period or income covered | Usual filing deadline Comprehensive income tax | Income from the previous year that must be combined | May 31 of the following year VAT for general taxpayers | Business activity in the first half of the year | July 25 of the same year VAT for general taxpayers | Business activity in the second half of the year | January 25 of the following year VAT for simplified taxpayers | Business activity during the year | January 25 of the following year Business premises status report for VAT-exempt businesses | Previous year's income and business premises status | February 10 of the following year
The table shows the standard schedule. Check separately for holidays and any extensions that apply to you. Simplified VAT taxpayers may also need to file an interim return if their classification changes or in other circumstances. Individual general VAT taxpayers should also check whether they must make a payment under a preliminary tax notice. National Tax Service VAT filing schedule
VAT-exempt YouTubers must also submit a business premises status report. The National Tax Service instructed them to report their 2025 activity by February 10, 2026. The report covers income, major expenses, facilities, employment status, and other details. National Tax Service guidance on 2026 business premises status reporting
How does the National Tax Service identify overseas income?
The National Tax Service uses tax information such as foreign exchange records and electronic tax invoices. It also uses credit card records to check what has been reported. Receiving income in a personal bank account does not remove the obligation to report it. National Tax Service guidance on reporting YouTuber income
US$10,000 is not an exemption threshold for YouTuber income tax. A bank's reporting threshold is separate from the obligation to report income. Taxable income must be reported even if the foreign currency received is less than that amount. Check your bank's foreign exchange guidance for its specific reporting requirements.
Checking overseas withholding and bank deposits
Using only bank deposits to record overseas earnings can result in discrepancies. Google may withhold U.S. tax before making a payment. Withholding means the payer deducts tax in advance and pays it to the tax authority. Check Google's payment reports for the final withholding details. YouTube U.S. tax requirements
The following table lists items to check when comparing settlement records.
Record | What to check | Why it matters Platform payment report | Earnings and withholding details | Distinguish pretax earnings from the amount received Bank deposit records | Amount actually received and fees | Identify differences from the settlement amount U.S. tax documents | Income and tax paid for the year | Assess eligibility for a foreign tax credit Domestic sponsorship settlement statements | Payments and domestic withholding | Compare separately with overseas income
Even if you paid tax in the United States, you must separately check your Korean filing obligations. The foreign tax credit is a system for addressing double taxation. It has eligibility requirements and a deduction limit, so do not assume you can claim a credit for the full amount. The National Tax Service explains how to calculate the limit in its tax guide for creators. National Tax Service guidance on foreign tax credits
Common mistakes when YouTubers file taxes
A common mistake is confusing the obligation to file with the amount of tax actually owed. A low calculated tax amount does not remove the filing obligation. Failure to report income or underreporting it can result in penalties. National Tax Service guidance on comprehensive income tax for YouTubers
Common misconception | What to check VAT-exempt businesses do not have to file taxes | Check comprehensive income tax and business premises status reporting requirements An employer's year-end tax settlement also covers side income | Check comprehensive income tax requirements, including video business income Contributions to a personal bank account do not need to be reported | Check whether the income is related to broadcasting activities Spending a lot on business expenses results in a refund | Compare the final tax amount with taxes already paid U.S. withholding means no Korean filing is needed | Check Korean filing requirements and eligibility for a foreign tax credit
You can prepare to file in the following order:
· Check the industry and tax classification on your business registration certificate. · Gather platform settlement statements and sponsorship and contribution records. · Record income and business expenses in your accounting records. · Compare domestic and overseas withholding records separately. · Check the National Tax Service's filing deadline for the relevant tax year. (Verified: The comprehensive income tax filing deadlines currently provided by the National Tax Service for the 2025 tax year are June 1, 2026, for general filers and June 30, 2026, for those submitting a confirmation of accurate tax filing · Source nts.go.kr · Checked 2026-10-05)
0:00 0:00
1 / 57

Advertisement

Download text

File name
youtuber-tax-income-vat-business-registration-en.txt
Format
TXT (text/plain)
Paragraphs
57

Downloads exactly what you see as a text file.

Please cite the source when quoting.

Large text

Makes the text larger and the colors clearer. Turn it on if the text feels too small.

Recurring income from sponsored videos must be reported as business income.

Key points

  • If you earn income from videos on an ongoing, recurring basis, you must register as a business.
  • Businesses exempt from VAT must still check their comprehensive income tax and business status reporting obligations.
  • The general threshold for simplified taxation, expanded in July 2024, is total sales of less than 104 million won in the previous year.
  • Comprehensive income tax is calculated after accounting for necessary expenses, deductions, and other factors, not on sales alone.
  • Google's U.S. tax withholding does not replace reporting income in Korea.

YouTubers who regularly earn income from advertising, sponsorships, or viewer contributions must file taxes. VAT-exempt businesses must also file comprehensive income tax returns. The amount they actually pay depends on deductible business expenses and tax deductions. Whether they have employees and facilities determines their business classification.

The simplified VAT threshold follows the standard revised in July 2024, and the filing dates follow National Tax Service guidance for the 2025 tax year.

What YouTuber income must be reported?

Income earned repeatedly from video activities for profit is business income. It is wrong to assume that only advertising income must be reported. Contributions that viewers send to a personal bank account in connection with broadcasts are also included. The National Tax Service says this income must be reported on a comprehensive income tax return. National Tax Service guidance on comprehensive income tax filing

Type of income Records to check
YouTube advertising income Platform earnings and payment statements
Corporate sponsorships and fees for promotional videos Contracts and settlement statements
Platform contributions and contributions to personal bank accounts Contribution records and bank account transactions
Income from events, lectures, and other activities Payment statements and contract terms

The National Tax Service identifies advertising, contributions, corporate promotions, and events as types of creator income. However, one-off activities may be classified differently. If it is difficult to determine whether an activity is an ongoing business, organize your activity records and check. National Tax Service overview of solo media creators

Do employees and minors also have to file?

People with regular jobs should also check whether they need to file a comprehensive income tax return if they earn recurring income from videos. Their employer's year-end tax settlement does not cover video business income. A comprehensive income tax return also reflects employment income that must be combined with other income. National Tax Service overview of comprehensive income tax

Being a minor does not, by itself, exempt taxable income. If family members run a channel together, however, they must determine to whom the income actually belongs. If the person appearing on the channel, the person signing contracts, and the person receiving the income are different, check with the tax office responsible for your area.

Google’s US tax withholding does not replace reporting income in South Korea.

Business registration and taxable versus exempt status

If you earn income from videos on an ongoing, recurring basis, you must register as a business. Registration is not a procedure you choose only when it offers tax savings. Whether a business is taxable or exempt is determined by its actual employment arrangements and business facilities.

The National Tax Service's “Tax Guide for Solo Media Creators” states:

Both taxable and exempt businesses must file comprehensive income tax returns.

Classification Criteria Industry code Basic filings
Media content creation business Employs staff or has physical facilities for business use 921505 VAT and comprehensive income tax
Solo media content creator Has neither employees nor physical facilities for business use 940306 Business premises status report and comprehensive income tax

Running a channel alone does not automatically make you a VAT-exempt business. The National Tax Service gives professional filming equipment and a separate studio as examples of physical facilities. If it is unclear whether facilities are used exclusively for business, check before registering. National Tax Service tax guide for solo media creators

How is simplified VAT taxation different from exemption?

Simplified VAT taxation simplifies how VAT is calculated. Exemption means VAT does not apply to the services in question. The two systems differ starting with the criteria used to determine eligibility.

The general threshold for simplified VAT taxation is less than 80 million won in the previous year's sales, including VAT. The threshold was expanded in July 2024, so you should not simply apply the previous 80 million won threshold. National Tax Service guidance on changes to simplified VAT taxation

Classification What to check Exempt from comprehensive income tax?
VAT-exempt business Type of services provided and requirements concerning personnel and physical facilities No
Simplified VAT taxpayer Sales threshold and exclusions from simplified VAT taxation No
General VAT taxpayer VAT classification, including eligibility for simplified VAT taxation No

Even if sales meet the threshold, simplified VAT taxation may be unavailable because of the type of business or other factors. Check your business registration to see which classification applies. You can also check the eligibility requirements in the National Tax Service's VAT guidance. National Tax Service overview of VAT

Zero rating for overseas advertising income

Overseas advertising income may qualify for zero-rated VAT if it meets the requirements. Zero rating applies a VAT rate of 0%. Unlike an exemption, it is a taxable transaction, so filing and supporting documentation are required. Do not treat domestic sponsorship income the same way. National Tax Service VAT guidance for creators

How much tax do YouTubers pay?

Monthly income alone cannot determine the final comprehensive income tax amount. Business income is calculated by subtracting deductible business expenses from gross income. Other income that must be combined with it, along with deductions, is then taken into account. This is why people with the same sales can owe different amounts.

When filing based on accounting records, the basic calculation follows these steps:

  1. Add together business income from advertising, sponsorships, contributions, and other sources.
  2. Subtract allowable business expenses to calculate business income.
  3. Account for other income that must be combined with it and for income deductions.
  4. Apply the tax rate, then account for tax credits and taxes already paid.

Deductible business expenses are costs incurred for the business. Accounting records of income and expenses provide the basis for the calculation. The type of records required depends on factors such as the type of business and income level. National Tax Service guidance on accounting records and foreign tax credits

Are all video production costs deductible?

You cannot report personal living expenses as video production costs. For meals or purchased items, check whether the expense was actually related to the business. Keep receipts and record what the expenses were for. National Tax Service response concerning business owners' meal expenses

  • Editing and production service fees: Check contracts and proof of payment
  • Filming location rental: Check the lease and records of business use
  • Equipment purchases: Check whether the equipment is used for business and how the cost should be recorded
  • Expenses with both personal and business use: Separate the business-related portion

High expenses alone do not create a tax refund. A refund arises if taxes already paid exceed the final tax assessed. Business income subject to 3.3% withholding in Korea must also be included in the final calculation. National Tax Service guidance on prefilled tax returns

Comprehensive income tax and VAT filing schedules

The usual comprehensive income tax filing period is May of the year after the income is earned. The statutory period runs from May 1 through May 31. Those submitting a confirmation of accurate tax filing have until June 30. If a deadline falls on a Saturday or public holiday, it is extended to the following day.

The general filing deadline for the 2025 tax year was June 1, 2026. Income earned in 2026 must, in principle, be reported in May 2027. Check the National Tax Service's filing guidance for year-specific exceptions. (Verified: For some taxpayers eligible for tax administration support for the 2025 tax year, the payment deadline was extended by 3 months from June 1, 2026, to August 31, 2026 · Source nts.go.kr · Checked 2026-10-05) National Tax Service comprehensive income tax filing and payment deadlines

Filing type Period or income covered Usual filing deadline
Comprehensive income tax Income from the previous year that must be combined May 31 of the following year
VAT for general taxpayers Business activity in the first half of the year July 25 of the same year
VAT for general taxpayers Business activity in the second half of the year January 25 of the following year
VAT for simplified taxpayers Business activity during the year January 25 of the following year
Business premises status report for VAT-exempt businesses Previous year's income and business premises status February 10 of the following year

The table shows the standard schedule. Check separately for holidays and any extensions that apply to you. Simplified VAT taxpayers may also need to file an interim return if their classification changes or in other circumstances. Individual general VAT taxpayers should also check whether they must make a payment under a preliminary tax notice. National Tax Service VAT filing schedule

VAT-exempt YouTubers must also submit a business premises status report. The National Tax Service instructed them to report their 2025 activity by February 10, 2026. The report covers income, major expenses, facilities, employment status, and other details. National Tax Service guidance on 2026 business premises status reporting

How does the National Tax Service identify overseas income?

The National Tax Service uses tax information such as foreign exchange records and electronic tax invoices. It also uses credit card records to check what has been reported. Receiving income in a personal bank account does not remove the obligation to report it. National Tax Service guidance on reporting YouTuber income

US$10,000 is not an exemption threshold for YouTuber income tax. A bank's reporting threshold is separate from the obligation to report income. Taxable income must be reported even if the foreign currency received is less than that amount. Check your bank's foreign exchange guidance for its specific reporting requirements.

Checking overseas withholding and bank deposits

Using only bank deposits to record overseas earnings can result in discrepancies. Google may withhold U.S. tax before making a payment. Withholding means the payer deducts tax in advance and pays it to the tax authority. Check Google's payment reports for the final withholding details. YouTube U.S. tax requirements

The following table lists items to check when comparing settlement records.

Record What to check Why it matters
Platform payment report Earnings and withholding details Distinguish pretax earnings from the amount received
Bank deposit records Amount actually received and fees Identify differences from the settlement amount
U.S. tax documents Income and tax paid for the year Assess eligibility for a foreign tax credit
Domestic sponsorship settlement statements Payments and domestic withholding Compare separately with overseas income

Even if you paid tax in the United States, you must separately check your Korean filing obligations. The foreign tax credit is a system for addressing double taxation. It has eligibility requirements and a deduction limit, so do not assume you can claim a credit for the full amount. The National Tax Service explains how to calculate the limit in its tax guide for creators. National Tax Service guidance on foreign tax credits

Common mistakes when YouTubers file taxes

A common mistake is confusing the obligation to file with the amount of tax actually owed. A low calculated tax amount does not remove the filing obligation. Failure to report income or underreporting it can result in penalties. National Tax Service guidance on comprehensive income tax for YouTubers

Common misconception What to check
VAT-exempt businesses do not have to file taxes Check comprehensive income tax and business premises status reporting requirements
An employer's year-end tax settlement also covers side income Check comprehensive income tax requirements, including video business income
Contributions to a personal bank account do not need to be reported Check whether the income is related to broadcasting activities
Spending a lot on business expenses results in a refund Compare the final tax amount with taxes already paid
U.S. withholding means no Korean filing is needed Check Korean filing requirements and eligibility for a foreign tax credit

You can prepare to file in the following order:

  1. Check the industry and tax classification on your business registration certificate.
  2. Gather platform settlement statements and sponsorship and contribution records.
  3. Record income and business expenses in your accounting records.
  4. Compare domestic and overseas withholding records separately.
  5. Check the National Tax Service's filing deadline for the relevant tax year. (Verified: The comprehensive income tax filing deadlines currently provided by the National Tax Service for the 2025 tax year are June 1, 2026, for general filers and June 30, 2026, for those submitting a confirmation of accurate tax filing · Source nts.go.kr · Checked 2026-10-05)
Open the link

Opens in a new window.

Advertisement

Sign-in required

Sign in with your Google account to like, comment, and save highlights.

FAQ

Do YouTubers need to register as a business?

If you produce videos regularly and repeatedly to earn income, you must register as a business. Whether you have employees and business facilities determines whether your business is taxable or tax-exempt.

Are tax-exempt YouTubers also exempt from comprehensive income tax?

The exemption applies to value-added tax. Tax-exempt YouTubers must also file a comprehensive income tax return and check whether they need to file a business status report.

Is the annual sales threshold for simplified taxation of YouTubers 80 million won?

That was the previous threshold. The general threshold expanded in July 2024 is total consideration for supplies of less than 104 million won in the previous year. You must also check whether any exclusions based on your type of business or other factors apply.

What if an employee earns YouTube income as a side job?

Recurring income from producing videos is business income subject to comprehensive income tax filing. Separately from your employer's year-end tax settlement, you must include employment income and business income that must be combined.

Do YouTubers who are minors have to pay taxes?

Taxable income is not exempt simply because the YouTuber is a minor. If it is unclear who earned the income, such as when family members run the channel together, you must check the contracts and payment records.

Do I have to report donations received through a personal bank account?

Donations received in connection with broadcasting activities must be reported. They are not excluded simply because they were received through a personal bank account or called donations.

Can I skip filing a comprehensive income tax return if my income is low?

You cannot skip filing simply because your income is low. Even if the amount of tax due is small after expenses and deductions, whether you must file is determined separately.

If 3.3% was withheld from a sponsorship payment, has it already been reported?

The 3.3% withheld from business income is tax paid in advance. It is reconciled with your final tax liability when you file your comprehensive income tax return, and you may owe more tax or receive a refund.

If a payment received from abroad is less than US$10,000, can I leave it unreported?

US$10,000 is not an income tax exemption threshold. You must report taxable income from videos regardless of the threshold at which banks report payment information.

If Google withheld US tax, what happens to my Korean taxes?

US tax withholding does not replace reporting the income in Korea. You must check the relevant income and proof of tax paid to assess the eligibility requirements and limits for the foreign tax credit.

What was the comprehensive income tax filing deadline for YouTube income earned in 2025?

The general filing deadline was June 1, 2026. For taxpayers required to submit a confirmation of accurate tax filing, the deadline was June 30, 2026.

Sources

Data formats

This content is available in several machine-friendly formats.

Data-only languages (machine translated, files only)

Indonesian JSON MD Portuguese JSON MD Chinese (Traditional) JSON MD Deutsch JSON MD

Verification

This article was drafted with AI and then reviewed and edited by a person.

Reviewed by 신익희 · 편집장 · 2026-10-05

Figures in this article were checked against the source material during generation. 1 correction(s) applied. · 2026-10-05

This translation has been cross-checked by AI. · 2026-10-05

Reuse & AI usage

Search indexing and AI citation with attribution are welcome. See the license policy for details.

CC BY · License

Loading…

Loading…

Loading…

Related content

From Injoys

Request the content you want and take 70% of what it earns

Just leave the subject. We handle production, review, translation and distribution.

See how revenue sharing works

Comments